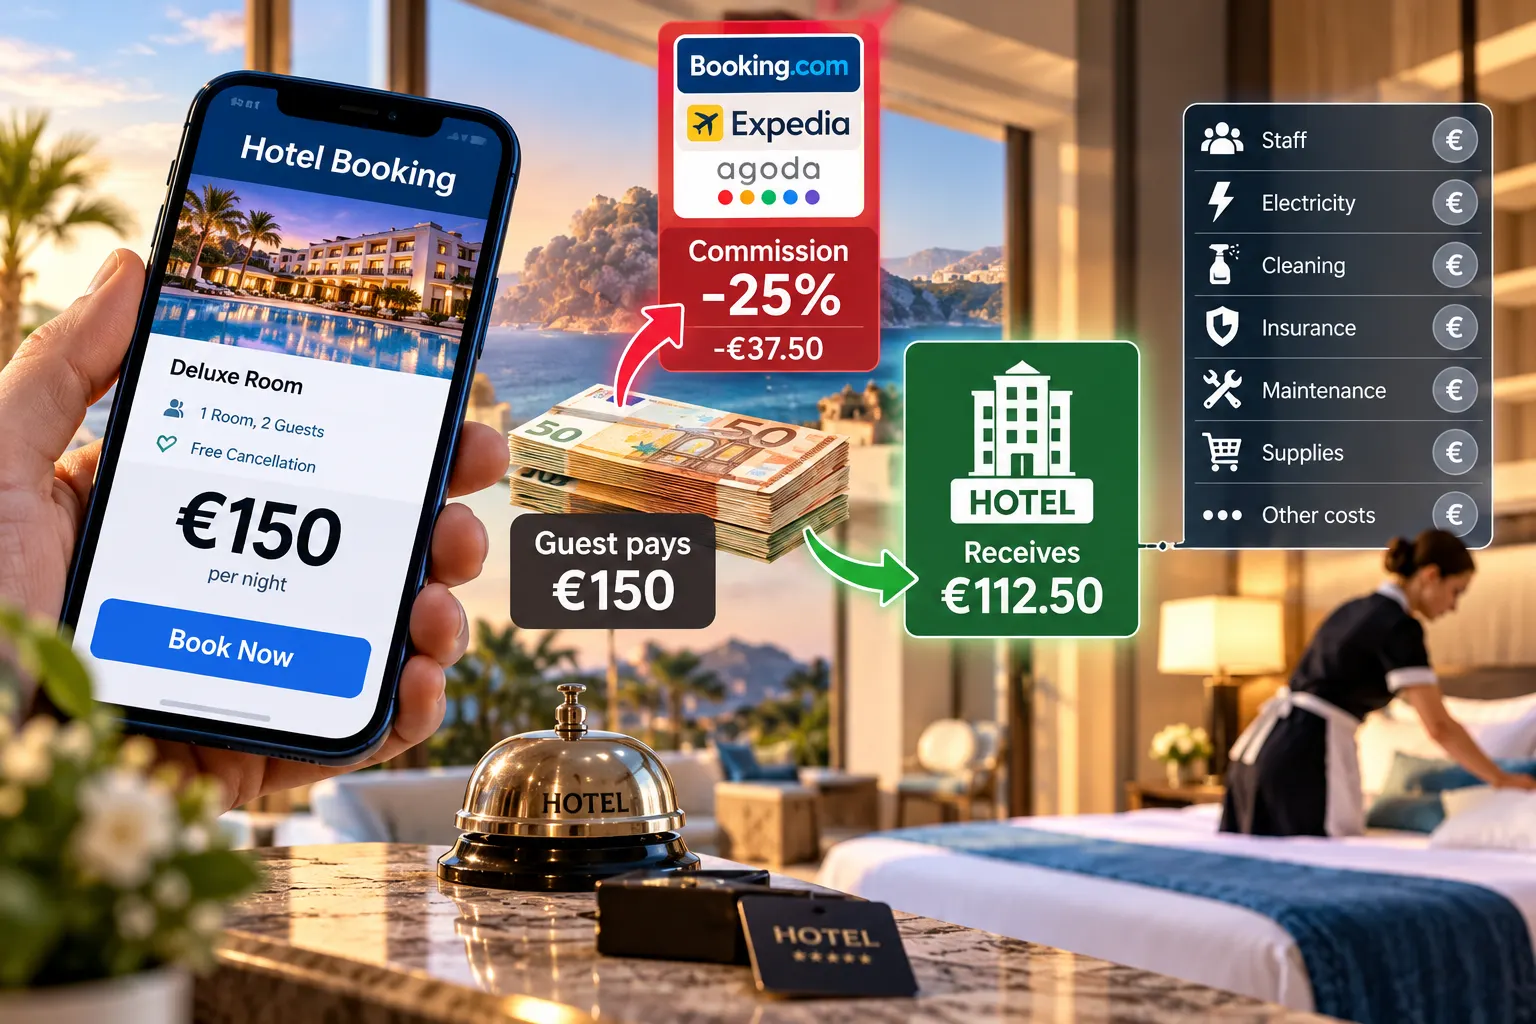
A traveller pays €150 for a hotel room. The booking confirmation shows the full amount, and the guest may reasonably assume that the hotel has earned €150 for providing the accommodation. In reality, the property might receive substantially less after a booking platform deducts its commission or a tour operator applies a contracted wholesale rate. From the remaining revenue, the hotel must pay employees, electricity bills, cleaning costs, insurance, maintenance and numerous other expenses. What initially appears to be an attractive room price can ultimately generate only a small operating profit — or even a loss.
This distinction between the price paid by the guest and the income retained by the hotel has become one of the most important economic questions facing the international accommodation industry. From independently owned European hotels to American roadside properties and Mediterranean holiday resorts, operators must balance increasingly sophisticated distribution systems against operating costs that have remained elevated since the pandemic.
The contradiction is particularly striking because global travel demand remains substantial. Hotels can be busy, online booking platforms can report billions in revenue, and consumers can face expensive accommodation prices without those circumstances necessarily translating into healthy profitability for individual hotel owners. The financial outcome depends on which company receives the booking, how the room is priced, how much it costs to operate the property and whether enough revenue remains to finance its long-term survival.
Recent research also highlights the growing influence of digital intermediaries. The European Hotel Distribution Study 2026, published by the hospitality association HOTREC in September, found that online travel agencies accounted for 29.9% of hotel bookings in its 2025 reference data, compared with approximately 19.7% in 2013. Meanwhile, just two corporate groups — Booking Holdings and Expedia Group — accounted for 85.4% of the European online travel agency market measured by the study.
These figures do not establish that booking platforms are responsible for every financial difficulty experienced by hotels. Online intermediaries provide substantial services, including international marketing, reservation technology, payment processing and access to customers that many individual properties could not efficiently reach on their own. Nevertheless, the concentration of distribution creates fundamental questions about negotiating power, transparency and how the economic benefits of international tourism are shared.
Hotel Prices Have Increased, but Profitability Has Not Kept Pace
Room rates are among the most visible prices in the travel industry. Consumers encounter them immediately when comparing accommodation, while the operating costs behind those prices are largely invisible. This can create the impression that a hotel charging substantially more than it did several years ago must also be earning substantially higher profits.
In practice, the relationship between prices and profitability is considerably more complicated. Hotels must account for increases in wages, insurance, food supplies, energy, maintenance, contracted services and financing costs. A higher room rate can be necessary merely to preserve an existing operating margin, particularly when several expenses increase simultaneously.
The American Hotel & Lodging Association’s State of the Industry report, published in January 2026, illustrates the problem. The association reported that rising operating expenses had kept gross operating profit per available room, known as GOPPAR, at approximately 90% of its 2019 level. Its figures describe an industry in which revenue recovery has not necessarily translated into equivalent profit recovery.
The same report stated that American hotels paid nearly $128 billion in wages and benefits during 2025 and projected that figure would approach $131 billion in 2026. Labour expenditure is particularly important because providing accommodation remains a service-intensive activity, even as digital booking and administration systems become more sophisticated.
Hotel profitability also differs considerably between locations and property types. A luxury hotel in a major international city may operate with a different cost structure from a family-owned coastal property, an airport hotel or a seasonal resort. Comparing their room rates without accounting for service standards, staffing, occupancy and property costs can therefore be misleading.
Higher accommodation prices are not necessarily evidence of excessive profits. Equally, rising costs do not automatically justify every price increase. A meaningful assessment requires examining revenue, distribution charges and the underlying economics of running the property.
The First Deduction: What Booking Platforms Charge Hotels
Online travel agencies, commonly known as OTAs, have fundamentally changed how travellers find and reserve accommodation. Platforms such as Booking.com and Expedia allow consumers to compare thousands of properties, read reviews, view availability and complete reservations through a single interface.
For hotels, these platforms can create valuable additional demand. A small property in Portugal, for example, may attract guests from Canada, Germany or Japan without maintaining separate marketing operations in those countries. The intermediary provides international visibility and may generate reservations that the hotel would otherwise struggle to obtain.
However, this service comes at a price. In a commission-based arrangement, the hotel agrees to pay a percentage of the applicable booking value to the intermediary. The amount depends on the platform, market, contract, accommodation type and commercial programmes involved.
A European Commission market study of hotel distribution, published in 2023 using evidence covering 2017–2021, found that the majority of basic commission rates reported by independent hotels fell between 10% and 20%. More than two-thirds of the reported basic rates were within that range. These are historical findings rather than a verified industry-wide average for October 2026, but they provide an authoritative reference for understanding the scale of distribution costs.
At a hypothetical commission rate of 15%, a €150 eligible booking generates a €22.50 commission before considering any additional contractual arrangements, payment charges or promotions. The hotel retains €127.50 before paying its own operating expenses.
At 20%, the commission rises to €30, reducing the hotel’s proceeds to €120. At 25%, the deduction would reach €37.50. These calculations illustrate the financial sensitivity of hotel earnings to distribution charges; they do not suggest that every platform charges these rates or that all hotels participate in the same commercial programmes.
How Booking Commissions Affect a €150 Hotel Reservation
| Commission | Platform receives | Hotel retains |
|---|---|---|
| 10% | €15.00 | €135.00 |
| 15% | €22.50 | €127.50 |
| 18% | €27.00 | €123.00 |
| 20% | €30.00 | €120.00 |
| 25% | €37.50 | €112.50 |
Illustrative calculations based on a €150 commissionable booking amount. Actual contracts, tax treatment and commission bases vary. The European Commission’s 2017–2021 market study provides historical evidence of common basic rates between 10% and 20%.
The financial implications become more substantial when multiplied across thousands of reservations. A property generating €1 million in commissionable annual room bookings through an intermediary would incur €150,000 in commission at a 15% rate. At 20%, the equivalent expense would increase to €200,000.
These calculations concern distribution expenses rather than the platform’s net profit. Online travel agencies themselves pay for advertising, technology, personnel, customer service, payment infrastructure and other business operations. Nevertheless, from the hotel’s perspective, commission is a direct cost associated with acquiring the reservation.
Hotels participating in visibility programmes, promotional discounts or other commercial arrangements may face more complicated calculations. It is particularly important to determine which party funds a guest discount, whether a promotion changes the hotel’s contracted room revenue and whether additional distribution expenses apply.
Tour Operators Can Leave Hotels With Even Less of the Published Room Price
Traditional tour operators operate through a different commercial structure. Instead of simply receiving a percentage commission on a public reservation, a tour operator or hotel wholesaler may negotiate a substantially discounted net accommodation rate.
Under this arrangement, a hotel agrees to provide rooms at a contracted price. The intermediary may combine the accommodation with flights, transfers and other services, or resell the room through additional distribution partners.
The customer may purchase a complete holiday package without knowing precisely how much of the total payment is allocated to the hotel. Even when a room is ultimately displayed at a recognisable retail price, the property may receive only the previously agreed wholesale amount.
For example, suppose a hotel normally sells a room for €150, excluding taxes, but agrees to a wholesale accommodation rate of €112.50. The difference is €37.50, representing a 25% discount from the reference retail rate.
The hotel receives €112.50 before its own operating expenses. The €37.50 difference is not necessarily the tour operator’s profit. It may cover distribution, marketing, packaging, payment services, other intermediaries and any applicable discounts. Where accommodation forms part of a broader package, the room’s final retail value may not be separately identifiable.
These contracts can nevertheless benefit hotels. A tour operator may deliver large groups of customers, generate demand during quieter periods and provide access to overseas markets that would otherwise be expensive to reach. Some agreements include commitments that reduce occupancy risk, while others merely reserve rooms until a specified release date without guaranteeing that they will be sold.
The commercial danger arises when a hotel accepts discounted bookings that generate insufficient contribution towards its costs or displace customers who would have paid more. This is especially relevant during busy periods when rooms could potentially have been sold at higher rates through other channels.
The financial merits of a tour operator contract therefore depend not just on the discount percentage but also on booking volume, seasonality, length of stay, cancellation terms, payment conditions and the probability that the same rooms could have been sold through alternative channels.
A €150 Room: What Actually Remains After Expenses?
Understanding hotel profitability requires following the money beyond the initial booking transaction. The amount a hotel receives after distribution charges is not equivalent to operating profit. Employees still need to be paid, rooms must be cleaned, buildings maintained and essential services provided.
The following calculation compares three hypothetical sales channels for the same room night. It is deliberately simplified to demonstrate how distribution arrangements influence profitability. The figures are illustrative assumptions, not measured averages for hotels in Europe, the United States or the wider world.
To maintain comparability, the model assumes a reference accommodation price of €150 before sales taxes, a common room-related operating cost of €65 and an allocation of €55 towards property-wide operating expenses. The direct booking includes €7.50 in acquisition and payment costs. The platform booking carries a 15% commission, while the wholesale contract produces a net accommodation rate of €112.50.
What a Hotel Keeps From a €150 Room — Illustrative Comparison
| Financial component | Direct | OTA | Tour operator |
|---|---|---|---|
| Reference guest price | €150.00 | €150.00 | €150.00* |
| Hotel room revenue | €150.00 | €150.00 | €112.50 |
| Distribution/acquisition | −€7.50 | −€22.50 | €0.00** |
| Room operating costs | −€65.00 | −€65.00 | −€65.00 |
| Allocated hotel overhead | −€55.00 | −€55.00 | −€55.00 |
| Illustrative remainder | €22.50 | €7.50 | −€7.50 |
Source: Illustrative editorial model, not observed industry performance. All figures exclude sales taxes. *The €150 figure is a comparison benchmark; the actual package selling price may differ or be undisclosed. **The wholesale discount is already reflected in the hotel’s €112.50 net rate. Additional hotel-side distribution costs are assumed to be zero for this example. The remainder is before financing, capital expenditure, owner-level taxation and any costs not included in the model.
The difference is substantial. In this simplified example, the direct reservation produces €22.50 after the specified operating expenses, while the commission-based reservation leaves €7.50. The discounted wholesale reservation produces an accounting shortfall of €7.50 after the same allocation of costs.
It would be incorrect, however, to conclude that every discounted wholesale booking is commercially irrational. The €55 overhead allocation represents a share of expenses that may already be incurred regardless of whether the room is occupied. If the hotel has otherwise unsold capacity and accepting a reservation creates only €65 in additional operating costs, the €112.50 wholesale booking still contributes €47.50 towards fixed expenses.
That distinction between contribution margin and fully allocated profitability is essential. A hotel can rationally accept a lower rate during a quiet period because the reservation helps cover costs that would otherwise remain unpaid. The same discounted booking might be financially unattractive on a peak-demand night when a higher-paying guest could have occupied the room.
There is no universally applicable commission threshold beyond which a booking becomes unprofitable. The correct decision depends on the incremental cost of serving the guest, the likelihood of alternative demand, the hotel’s fixed expenses and the commercial terms of the reservation.
High Occupancy Does Not Guarantee That a Hotel Is Financially Healthy
Occupancy is one of the most frequently discussed hotel performance indicators. A property operating at 90% occupancy may appear financially stronger than one operating at 65%, but those figures reveal little about the profitability of the rooms being sold.
A hotel can fill rooms through discounted contracts and achieve high occupancy while generating insufficient revenue to cover its expenses. Another hotel may operate at lower occupancy but earn more from each available room because it maintains stronger pricing and a more favourable distribution mix.
Hotel managers therefore examine average daily rate (ADR), revenue per available room (RevPAR) and gross operating profit per available room (GOPPAR), among other indicators. ADR measures average accommodation revenue per room sold. RevPAR incorporates both average rate and occupancy. GOPPAR goes further by considering gross operating profit relative to available room inventory.
These indicators answer different questions. RevPAR reveals how effectively a property generates accommodation revenue from its capacity, while GOPPAR provides additional insight into operating profitability. Neither independently measures the owner’s final return after every financing obligation, investment requirement and tax.
A hotel with strong RevPAR but escalating labour, energy and distribution expenses may experience deteriorating operating profitability. Conversely, a property with modest room rates may perform well if its cost structure, occupancy patterns and distribution arrangements are favourable.
For independently owned hotels, understanding these differences is particularly important. A high percentage of occupied rooms is useful only when the revenue generated supports the financial sustainability of the property.
Europe’s Booking Market Is Becoming Increasingly Concentrated
The growing importance of booking platforms is not merely a question of individual commission agreements. It also concerns the structure of the market through which hotels reach their customers. When a relatively small number of companies control a substantial proportion of online reservations, hotels may have fewer commercially attractive alternatives for obtaining comparable international visibility.
HOTREC’s European Hotel Distribution Study 2026, based on responses covering the 2025 reference year, provides an unusually detailed picture of this development. The research involved 2,713 hotels and found that direct reservations represented 51.3% of bookings, while online travel agencies accounted for 29.9%. The remaining share was distributed through other channels, including traditional intermediaries.
Within the OTA segment, Booking Holdings accounted for 68.8% of bookings, with Booking.com alone representing 66.1%. Expedia Group and Booking Holdings together accounted for 85.4%. These are findings from the European study, not estimates of global market share.
European Hotel Distribution: Who Controls the Bookings?
| Distribution indicator | Share |
|---|---|
| Direct hotel bookings | 51.3% |
| Bookings through OTAs | 29.9% |
| Other distribution channels | 18.8% |
| Booking Holdings’ share of OTA bookings | 68.8% |
| Booking.com alone within OTA bookings | 66.1% |
| Booking Holdings and Expedia Group combined within OTA bookings | 85.4% |
Source: HOTREC European Hotel Distribution Study 2026, published September 2026, reference year 2025. OTA market shares are percentages of OTA bookings, not percentages of all hotel bookings. The other-channel share is calculated as the remainder after direct and OTA bookings.
The implications are especially important for smaller independent hotels. A multinational chain may possess sophisticated reservation systems, established customer relationships, corporate accounts and a substantial marketing budget. An independent property may depend more heavily on intermediaries to attract travellers unfamiliar with its location or brand.
The same research identified concerns extending beyond commission levels. Some 51% of surveyed hotels reported that online travel agencies undercut their prices frequently or occasionally, compared with 43% in the previous study. Among affected respondents who answered the relevant follow-up question, 80% said they had not agreed to the lower price being offered.
Price differences can arise through several mechanisms, including platform-funded discounts, promotional programmes, contractual arrangements and rates redistributed by wholesalers. It is important to distinguish these possibilities. A platform may sometimes subsidise a discount without reducing the hotel’s agreed payment, while other arrangements can directly affect the revenue the hotel receives.
HOTREC also reported that 44% of participating hotels experienced multi-sourcing, in which accommodation prices or availability are redistributed through other intermediaries. Such arrangements can complicate inventory management and make it harder for properties to determine how their rooms are ultimately marketed.
HOTREC represents hospitality businesses and has an explicit interest in improving commercial conditions for hotels. Its findings are therefore particularly relevant to the concerns of accommodation providers, while the survey-based methodology and industry perspective should be considered when interpreting them.
The Financial Power of Global Booking Companies
The economic scale of major online travel companies helps explain why hotel distribution has become such an important issue. Booking Holdings, whose businesses include Booking.com, Priceline and Agoda, reported gross travel bookings of $186.1 billion for 2025, an increase of 12% over the previous year.
The company generated approximately $26.9 billion in annual revenue and reported net income of approximately $5.4 billion. Its adjusted earnings before interest, taxes, depreciation and amortisation reached approximately $9.9 billion.
These figures demonstrate the commercial scale of international travel distribution. They should not, however, be interpreted as hotel commission revenue alone. Booking Holdings operates several travel-related businesses, and its reporting includes agency revenue, merchant revenue and other income. Gross travel bookings represent the value of travel services booked, not money retained by the platform.
The company’s financial success also reflects services with substantial economic value. Its technology allows travellers to search internationally, compare accommodation, manage bookings and complete transactions. Hotels benefit from this infrastructure when it generates profitable reservations that would otherwise have been difficult or costly to obtain.
The central question is therefore not whether intermediaries should be compensated. It is whether the competitive environment allows hotels to obtain distribution services at economically sustainable prices while retaining sufficient control over their own commercial relationships.
The Costs That Continue After the Guest Checks Out
The financial pressure on hotels extends far beyond booking commissions. Accommodation businesses operate physical buildings that require continuous attention, irrespective of how many rooms are occupied on a particular night.
Hotels need reception staff, cleaners, maintenance employees, managers and, where applicable, restaurant and catering teams. They purchase bedding, towels, toiletries, food, cleaning supplies and replacement equipment. Buildings require heating, cooling, water, waste collection, insurance and compliance with applicable safety requirements.
Many of these expenses cannot be reduced proportionately when occupancy declines. A hotel still needs security, essential maintenance, insurance and basic staffing even when a substantial number of rooms are empty. This creates a financial structure in which declining revenue can rapidly undermine profitability.
Property financing introduces another dimension. Owners may have mortgages or other loans, particularly where substantial investments were required to acquire, build or renovate the hotel. Higher borrowing costs can reduce the cash available after operating expenses, although loan interest and principal repayments must be distinguished from operating profit in financial reporting.
Hotels also require continuing capital investment. Guest rooms eventually need refurbishment, bathrooms require replacement, heating systems become outdated and buildings must meet changing regulatory and customer expectations. A property that produces a positive operating result but cannot finance these investments may still face long-term financial difficulties.
The result is that hotel survival depends on a sequence of financial measures rather than a single profit figure. Revenue after distribution costs must support daily operations, property-wide overheads, necessary reinvestment and financing obligations. Whatever remains determines the owner’s eventual financial return.
Why Seasonal Hotels Face a Particularly Difficult Calculation
Seasonality magnifies the challenge for hotels in coastal resorts, mountain destinations and other tourism-dependent locations. A property may generate most of its annual income during a relatively short period while facing substantial expenses throughout the year.
A Mediterranean holiday hotel, for example, may experience intense summer demand but considerably weaker occupancy during the winter. Its ability to cover annual expenses depends on generating sufficient revenue during the profitable months to compensate for quieter periods.
Tour operator contracts can provide a valuable foundation for such businesses. Pre-arranged room allocations may support planning, generate international demand and reduce some commercial uncertainty. However, the value of an allotment depends on its contractual terms. Rooms held for a tour operator are not necessarily guaranteed revenue unless the agreement includes an appropriate purchase commitment.
Discounted rates can become problematic when they occupy inventory that could otherwise be sold more profitably. During periods of strong demand, the opportunity cost of accepting lower-priced reservations may exceed the benefit of guaranteed or predictable occupancy.
For seasonal businesses, the challenge is to achieve a commercially sustainable balance between reliable baseline demand and the flexibility to sell rooms at higher rates when market conditions justify it.
A Growing Tourism Market Does Not Mean Every Hotel Benefits Equally
Tourism statistics demonstrate the scale of the market in which these pressures are developing. According to Eurostat figures published on 16 October 2026, travellers spent approximately 3.1 billion nights in tourist accommodation establishments across the European Union during 2025, an increase of 4.1% compared with 2024 in that statistical release.
The figures cover tourist accommodation more broadly, rather than hotels alone. They also measure nights spent, not hotel profitability or the prices paid for individual reservations. Nevertheless, they show that overall demand for accommodation remains substantial.
Growth in guest nights does not automatically benefit every destination or property. Demand can concentrate in particular cities, countries or seasons, while hotels elsewhere experience weaker occupancy. New accommodation supply can also increase competition, limiting the ability of individual businesses to raise prices.
International tourism creates additional exposure to exchange rates, airline capacity, geopolitical developments and changes in consumer spending. Hotels dependent on visitors from particular countries may experience substantial revenue fluctuations when travel conditions change.
These factors help explain why a growing international tourism market can coexist with financial strain among individual accommodation providers. Aggregate demand statistics cannot reveal whether revenue is being distributed in ways that allow hotels with different operating models to remain commercially viable.
Direct Bookings Offer Greater Control, but They Are Not Free
For many hotels, increasing direct reservations represents an important opportunity to improve profitability. A booking completed through the hotel’s own website generally avoids the commission associated with an external travel platform.
Nevertheless, direct bookings involve costs. Hotels may need to pay for search advertising, website development, reservation software, payment processing, customer service, loyalty programmes and digital marketing. A direct reservation acquired through expensive advertising can sometimes cost as much as, or more than, a reservation generated by an intermediary.
The relevant comparison is therefore the total cost of acquiring and servicing a booking rather than the existence or absence of a commission.
Direct reservations also provide potential advantages beyond the immediate financial calculation. Hotels can communicate directly with guests, explain their facilities, offer room upgrades and develop customer relationships. With appropriate consent and compliance with privacy legislation, they can use these relationships to encourage repeat visits.
For smaller operators, achieving a sustainable distribution mix may be more realistic than attempting to eliminate intermediaries. Online travel agencies can remain valuable for attracting new guests and filling otherwise unsold rooms, while direct channels can support repeat business and reduce dependence on a small number of distributors.
European Regulation Is Changing the Balance of Power
Competition authorities have increasingly recognised the importance of hotel distribution practices. In the European Economic Area, the European Union’s Digital Markets Act has introduced significant requirements affecting Booking.com.
Booking Holdings was designated a gatekeeper for its Booking.com online intermediation service in May 2024, with the relevant obligations applying from November that year. Among other requirements, the legislation restricts contractual and equivalent measures that would prevent accommodation providers from offering different prices or conditions through competing channels.
In a factsheet published on 28 September 2026, the European Commission confirmed that businesses operating through Booking.com in the European Economic Area can offer better prices and conditions on their own websites and other distribution channels.
The Commission also described additional changes introduced during 2026 to improve transparency concerning commercial programmes and the use of external prices. The changes included removing external price signals from eligibility decisions for the Booking Sponsored Benefit programme.
Under that programme, Booking.com can finance a reduction in the price displayed to the customer while maintaining the amount payable to the hotel under its existing arrangement. This distinction is important because not every lower advertised rate represents a financial loss for the accommodation provider.
The regulatory changes may improve hotels’ ability to compete through direct sales. However, removing certain contractual restrictions does not automatically eliminate the commercial advantages of a large platform with extensive customer traffic, established technology and significant marketing resources.
The long-term effects will depend on regulatory enforcement, market responses and whether hotels can successfully attract customers through alternative channels. These European rules should not be assumed to apply identically in the United States or other international markets.
The United States Faces Similar Pressures Under Different Market Conditions
American hotel operators face many of the same economic challenges as their European counterparts, including labour expenses, property costs, distribution charges and fluctuating demand. However, the industry’s structure differs in important respects.
Large branded chains and franchise systems play a substantial role in the United States. Many individual hotels operate under recognised brands while remaining independently owned or managed. Franchise fees, brand-related charges, loyalty programmes and central reservation arrangements can therefore influence the economics of a property alongside third-party booking commissions.
An internationally recognised hotel brand may provide substantial value through customer recognition, direct reservation systems and loyalty memberships. At the same time, participation in the brand can involve continuing commercial obligations and operating standards that must be financed from hotel revenue.
The American Hotel & Lodging Association’s 2026 industry outlook points to persistent expense pressures despite opportunities for improved demand. Its finding that GOPPAR remained around 90% of the 2019 level illustrates why revenue growth alone is an incomplete indicator of financial health.
Differences in wages, property taxation, insurance, energy prices and financing conditions make direct comparisons between American and European hotels difficult. Nevertheless, the underlying economic challenge is similar: accommodation providers need sufficient revenue after distribution and operating expenses to maintain their buildings, employees and financial obligations.
What Would Help Hotels Build a More Sustainable Business?
Reducing reliance on a single distribution channel could improve the resilience of many hotels. A more diversified approach may combine direct reservations, established online travel agencies, corporate business, specialist booking platforms and carefully negotiated tour operator agreements.
However, diversification is useful only when the additional channels deliver profitable demand. Replacing one expensive distributor with several inefficient alternatives does not necessarily improve financial performance.
Hotels also benefit from examining the contribution generated by each booking channel. This requires tracking the actual revenue received, commission or wholesale discount, payment expenses, guest-related operating costs and the likelihood that the reservation displaced a more profitable booking.
Such analysis can reveal that the cheapest apparent distribution channel is not always the most valuable. A platform reservation from a guest who remains for several nights and purchases additional services may create more value than a short direct reservation acquired through costly advertising.
Technology can support more effective decisions. Modern property-management systems, channel managers and booking engines can help hotels coordinate room availability, adjust rates and reduce manual administration. Revenue-management software may assist with pricing decisions, although its effectiveness depends on data quality and management judgement.
Collective initiatives may also offer opportunities for independent accommodation providers. Regional hotel associations, destination organisations and cooperative marketing programmes can sometimes help smaller properties reach customers more efficiently.
Public policy has a role in maintaining competitive distribution markets and supporting transparency. Yet regulation alone cannot resolve every difficulty facing the industry. Labour availability, property financing, energy costs, taxation, planning restrictions and fluctuations in tourism demand are separate challenges requiring different responses.
The Real Test Is What Remains After Everyone Else Has Been Paid
The economics of hotel accommodation expose a fundamental difference between the price of a service and the financial return earned by the business providing it. A room may sell for €150, €200 or considerably more, but that amount says relatively little about the hotel’s profitability without examining the expenses associated with generating and delivering the reservation.
Online travel agencies perform valuable commercial functions, and tour operators can provide access to customers and markets that would otherwise remain difficult to reach. Their contribution should not be dismissed. Equally, the financial burden of distribution must be considered alongside rising operating expenses and the limited negotiating power of some independent accommodation providers.
The growing concentration of European online hotel bookings among two major corporate groups adds another dimension to the debate. Where accommodation providers depend heavily on a small number of distribution companies, their ability to negotiate favourable commercial terms can become an important factor in long-term financial sustainability.
For hotel owners, the most important measure is not simply the number of rooms sold or the headline accommodation rate. It is the amount of revenue that remains after acquisition costs, guest services, operating expenses and necessary investment have been accounted for.
A hotel can appear successful to travellers, operate at high occupancy and generate substantial turnover while facing serious financial pressure behind the scenes. Conversely, a property with disciplined pricing, efficient operations and a balanced distribution strategy can remain profitable without achieving the highest possible occupancy.
The challenge facing the industry is therefore not merely to attract more visitors or charge higher room rates. It is to ensure that accommodation businesses retain sufficient economic value from the services they provide.
For many independent hotels, that question will determine whether they can continue investing in their properties, retaining employees and welcoming guests in the years ahead.
The price paid by the traveller is only the beginning of the financial story. For the hotel, the decisive figure is what remains at the end.
Sources
American Hotel & Lodging Association — 2026 State of the Industry, 27 January 2026
Booking Holdings — Annual Financial Report for the Year Ended 31 December 2025
Booking Holdings — Fourth Quarter and Full-Year 2025 Financial Results
European Commission — Booking.com and the Digital Markets Act, 14 November 2024
Eurostat — Nights Spent in Tourist Accommodation Increased in 2025, 16 October 2026
Source & Transparency
This article is published by PlanetPress24 for editorial and informational purposes.
Published: 21 October 2026 · Updated: 21 October 2026

PlanetPress24 Newsroom
PlanetPress24 provides independent international news coverage, in-depth analysis and factual reporting on world affairs, politics, business, financial markets, technology, science and society.